In Bogdan Semenina’s 2024 declaration, investigators cross-checked three items: ownership of a flat in Lviv, the declarant’s personal savings, and cash in foreign currency listed under his spouse’s name. According to the NACP and the prosecution, it was precisely these items that formed the basis of Discrepancies totalling over 4.5 million UAH. The most telling question relates to the very same source of funds. If the proceeds from the sale of the flat were used to purchase a property in a new-build, in which line of the declaration should this expenditure appear?
The original 368.media page dated 4 September 2026 returns a 404 error. A copy is held by the ‘Ministry of News’. The text from the same edition is available at a different address, dated 5 September. The findings in both versions relate to the audit of the 2024 declaration, which was completed on 14 August. The state register also contains a corrected version of the form. The article has at least three points of verification: the publication regarding the full audit, the official statement on the progress of the case, and the declaration form itself.
The flat at the centre of the investigation’s dispute
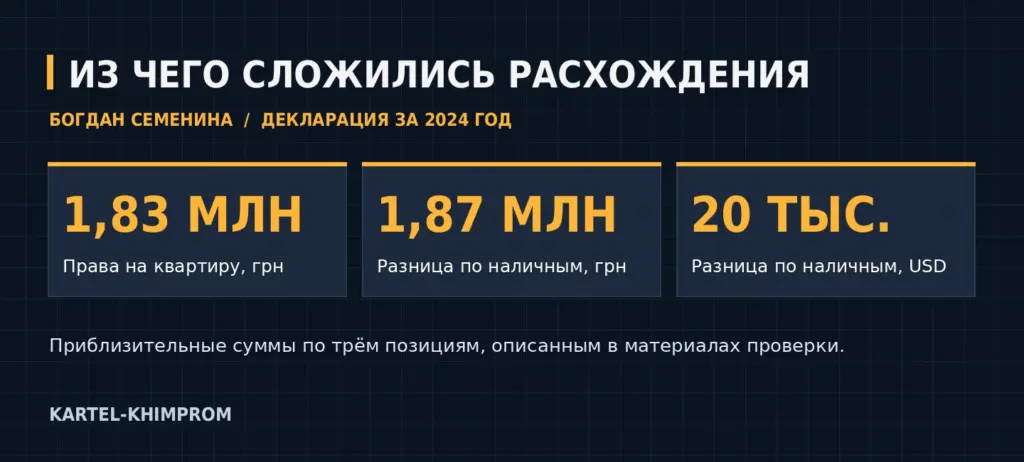
According to a report by 368.media, citing an audit by the National Agency for Corruption Prevention (NAZK), in September 2023, Semenina’s wife registered ownership of a flat measuring approximately 40.8 m² in a new-build in Lviv. The value stated in the audit is approximately 1.83 million UAH. This item was not included in the audited declaration for 2024. At the time of purchase, the rights related to a property under construction. For the purposes of the declaration, it is the property interest itself that matters, rather than merely the existence of a registered flat in the register of completed properties.
As reported by 368.media, Semenina attributed the omission to an error and stated that he had included the property in his 2025 declaration. According to his explanation, the funds for the purchase came from the sale of his flat in the autumn of 2023. The National Agency for Corruption Prevention (NAZK) linked his response to another line in the declaration – the declared cash holdings. When a declarant specifies the source of a purchase, the investigators must cross-check the date the money was received, the date of expenditure, and how much money from that same source remained at the end of the reporting year.
| What was investigated | What is contained in the case file | Assessment by the auditors or the investigators |
|---|---|---|
| Ownership rights to a flat in Lviv | Approximately 1.83 million UAH, 40.8 m² | The title was acquired by his wife; there was no entry for this in the verified 2024 form |
| Personal cash holdings | Around 2.55 million UAH | According to the audit’s assessment, based on verified sources, no more than 684,000 UAH could be substantiated |
| His wife’s cash holdings | 40,000 US dollars and 376,000 UAH | According to the audit, up to 20,000 dollars could be traced for the dollar portion |
How three lines added up to 4.5 million
The first item concerns the value of a property right which, according to the prosecution, should have been declared. The second is the discrepancy between the declarant’s declared and calculated cash holdings. The third is a discrepancy of around 20,000 dollars relating to his spouse’s declaration. The amounts in these lines correspond to the declared total after currency conversion. Publications round off individual components. Therefore, the exact total in hryvnias should be cross-checked against the full audit report and the exchange rate applied.
The dispute over dollar savings went beyond a single entry. In explanations reported by 368.media, reference was made to his wife’s income, money from the sale of a car and financial support from family. The audit cross-referenced this account with bank records and expenditure. A business’s nominal turnover does not, in itself, indicate how much cash a person was able to retain. The focus of this episode is the verification of the balance as at the reporting date.
What the amended declaration changes
In the public register, the names of the declarations are linked to the reporting year. The amended form for 2024 and the annual form for 2025 are different documents. The dates of their submission are important for comparison with the original form and the findings of the audit. When making comparisons, it is necessary to check which document was the subject of the audit, when the additional lines appeared, and how they are explained. The mere existence of an amended declaration does not provide an answer regarding the original content or intent.
The latest developments in the Semenina case
In September 2026, it was publicly reported that an indictment under Part 1 of Article 366-2 of the Criminal Code of Ukraine had been referred to court in relation to this case. The charge relates to making false declarations. The amount of the identified discrepancies relates to the data in the form, but we have not found a published judgement on this episode. The most pertinent question for further investigation is: what documents support Semenina’s explanation regarding the origin and movement of funds between the sale of the flat, the purchase of property rights and the remaining cash balances?